ICN News – Indonesia’s coal industry is once again in the spotlight following reports that prominent Indonesian businessman Andi Syamsuddin Arsyad, better known as Haji Isam, has offered approximately US$3 billion to acquire around 62% of PT Bayan Resources Tbk (BYAN).
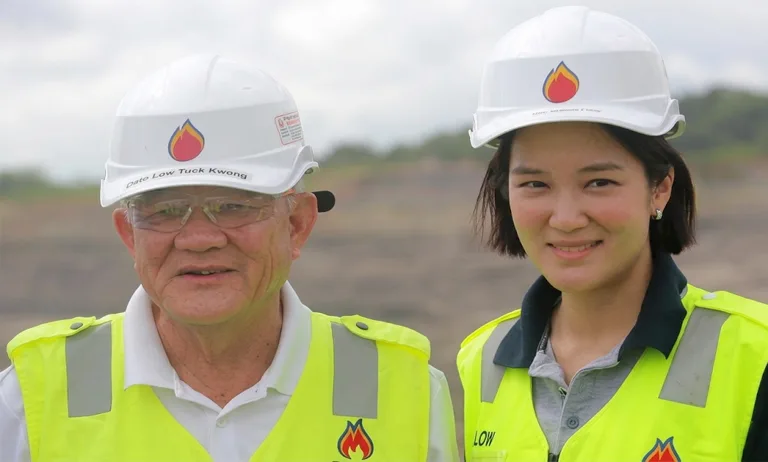
The reported offer has attracted significant attention because the stake represents a controlling block held by the family of Low Tuck Kwong, the founder and controlling shareholder of Bayan Resources. Low Tuck Kwong owns approximately 40.24% of Bayan, while his daughter, Elaine Low, holds around 22%. Combined, their holdings amount to approximately 62.2%.
However, the transaction should not yet be regarded as a completed acquisition. Recent reports indicate that discussions are still ongoing, with no certainty that an agreement will ultimately be reached. Bayan Resources has also previously informed the Indonesia Stock Exchange that its management was not aware of any takeover plan involving the structure and value being reported in the market.
US$3 BILLION BID TRIGGERS VALUATION DEBATE
If the reported US$3 billion offer is accurate, it would imply an overall valuation of approximately US$4.8 billion for Bayan based on a simple calculation. That figure is significantly below Bayan’s market capitalization, which was reported to be around US$26 billion when news of the offer emerged. On that basis, the reported offer would represent a discount of more than 80% to the company’s market value at the time.
The substantial gap has naturally attracted considerable market attention. However, a company’s stock-market valuation and the negotiated price for a controlling block cannot always be compared on a purely like for like basis. Bayan has a relatively limited free float, while a 62% stake provides control of the company. Long term coal market prospects, government production policies and prevailing coal prices are also factors that may influence the final negotiated valuation.
Earlier, in August 2026, a separate figure of approximately US$5.5 billion for the 62.2% Bayan stake had also circulated in the market. Therefore, the US$3 billion figure reported by Bloomberg in September represents a different development in the reported negotiations, rather than a transaction price that has been officially agreed.
BAYAN IS FAR MORE THAN AN ORDINARY COAL PRODUCER
The level of market interest is closely linked to Bayan Resources’ position as one of Indonesia’s largest coal producers. In 2025, Bayan achieved record coal production of 68.0 million tonnes, up 19.6% from 56.9 million tonnes in 2024. The company also generated approximately US$3.43 billion in revenue throughout 2025.
With annual production of 68 million tonnes, Bayan has established itself as one of the key players in Indonesia’s coal industry. Any significant change in its ownership structure or business strategy could therefore have a meaningful impact on the competitive landscape of the national coal sector.
Bayan also operates supporting infrastructure that forms an important part of its integrated business model, including coal terminals and logistics facilities. Consequently, the strategic value of Bayan extends beyond its mining operations to its ability to manage the coal supply chain from mine to shipment.
2026 PERFORMANCE CONTINUES TO SHOW GROWTH
Interestingly, while the market is closely watching reports of a potential change in ownership, Bayan’s financial performance through the first half of 2026 continued to demonstrate growth. As of June 30, 2026, Bayan reported revenue of approximately US$1.74 billion, representing an increase of around 7.29% from US$1.62 billion in the same period of 2025.
Net profit attributable to owners of the parent reached approximately US$410.25 million, up 17.46% from US$349.24 million in the first half of 2025. The growth indicates that Bayan continues to demonstrate strong revenue and earnings generation capacity.
In other words, the company at the centre of the reported acquisition discussions is not a business facing severe fundamental weakness. On the contrary, Bayan continues to operate at substantial production scale while delivering growth in both revenue and net profit during the first half of 2026.
IF SUCCESSFUL, HAJI ISAM WOULD BECOME AN EVEN MORE POWERFUL COAL PLAYER
If the transaction is ultimately completed, Haji Isam’s position in Indonesia’s coal industry would become considerably stronger. Jhonlin Group has long been active in the coal business through Jhonlin Baratama. Beyond mining, the group has expanded into a range of sectors, including logistics, agribusiness, palm oil, biodiesel and other natural-resource-related businesses.
Acquiring a 62% stake in Bayan would give Haji Isam control of a company producing tens of millions of tonnes of coal annually. Strategically, the combination of Jhonlin’s assets and Bayan’s operations would represent one of the most significant potential consolidations in Indonesia’s coal industry if the transaction materializes.
However, such a transaction would not automatically translate into higher national coal production. Actual output remains subject to government approved RKAB production plans, domestic market obligations (DMO), export policies, logistics capacity and prevailing coal-market conditions.
Therefore, if the transaction is completed, the market will closely monitor the subsequent strategy—particularly production targets, the expansion of the Tabang mining operation, sales strategy, infrastructure investment and the allocation of coal for both domestic and export markets.
US$3 BILLION TRANSACTION REMAINS UNCERTAIN
For Indonesia’s mining industry, the reported potential acquisition of Bayan Resources by Haji Isam is a major development that warrants close attention. If an agreement is reached, this would be far more than a simple change in share ownership. It could reshape the ownership structure and competitive dynamics among Indonesia’s leading coal producers. For now, however, US$3 billion remains a reported offer, not a finalized transaction value.
The market is still waiting for clarity on the final price, financing structure, parties involved and, most importantly, whether Low Tuck Kwong and his family are prepared to sell their controlling stake in Bayan at the reported offer price.
One thing is already clear: Bayan Resources possesses the scale and financial performance that make it one of Indonesia’s most strategically important coal assets. With 68 million tonnes of production and US$3.43 billion in revenue in 2025, followed by US$1.74 billion in revenue during the first six months of 2026, Bayan remains one of the country’s most significant coal companies.
If Haji Isam succeeds in acquiring the 62% stake, Indonesia’s coal industry could be entering a new chapter.
For advertising and subscriptions, please contact us via WA Or Email
Need a research report? Please visit CDMI Consulting