Reportedly Targeting a 62.2% Stake in Bayan Resources, Although Both Sides Deny Any Acquisition Plan
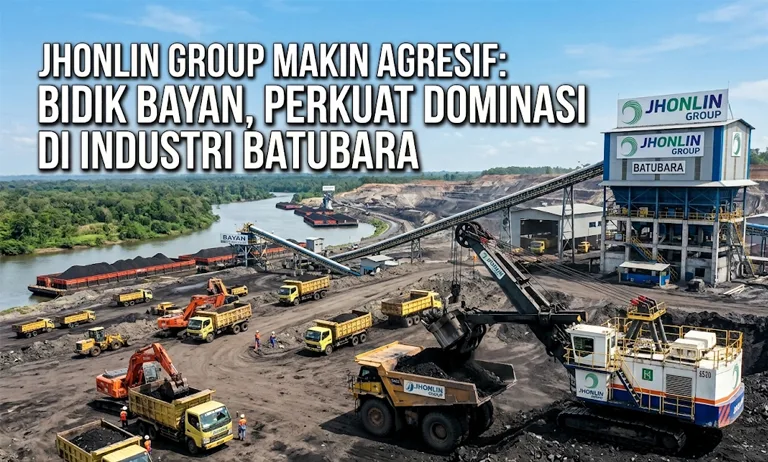
ICN News – Jhonlin Group is once again attracting attention across Indonesia’s mining industry. The business group controlled by South Kalimantan entrepreneur Andi Syamsuddin Arsyad, better known as Haji Isam, has come under the spotlight following reports of a potential acquisition of a controlling stake in PT Bayan Resources Tbk (BYAN).
According to market reports, Jhonlin Group is reportedly eyeing approximately 62.2% of Bayan Resources’ shares, in connection with the controlling ownership of the coal producer. The transaction value circulating in the market has reportedly reached around US$5.5 billion.
If such a transaction were ever to materialize, it would rank among the largest corporate transactions in Indonesia’s coal industry. However, the reported transaction has not been officially confirmed.
PT Jhonlin Agro Raya Tbk (JARR), a publicly listed company affiliated with Haji Isam, has clarified to the Indonesia Stock Exchange that the company and its group have no plans to acquire shares in Bayan Resources. Bayan Resources has also previously stated that it was not aware of any such acquisition plan.
Therefore, for now, the matter should be viewed as market speculation or a reported potential transaction, rather than a confirmed acquisition.
From 24 Million Tons to a 51 Million-Ton Production Quota
Regardless of the Bayan speculation, Jhonlin’s development in the coal sector is already significant enough to attract industry attention.
Jhonlin Group was reportedly producing approximately 24 million tons of coal in 2025. For 2026, the group has reportedly received approval for a production quota of up to approximately 51 million tons. These figures demonstrate that Jhonlin is no longer simply a regional player based in South Kalimantan. Its production scale has expanded to become an increasingly important force within Indonesia’s national coal industry.
This growth has also been supported by Jhonlin’s ability to build an integrated business ecosystem. Through various business entities, the group is involved not only in mining activities, but also in mining contracting, transportation, coal logistics and other supporting businesses.
Jhonlin Baratama is widely recognized as one of the key companies involved in the group’s mining operations. Its mining ecosystem also includes businesses engaged in logistics and shipping.
Therefore, Jhonlin’s strength is not solely based on coal reserves and production, but also on its ability to develop an integrated value chain covering mining, transportation and distribution.
Why Is Bayan So Attractive?
This is what makes Bayan Resources particularly interesting, Bayan Resources is one of Indonesia’s largest coal producers, with a highly integrated mining and infrastructure model. The company has developed major mining operations supported by transportation infrastructure and coal terminals. Its Tabang/Pakar operation in East Kalimantan has become one of the company’s key growth engines.
Bayan has stated that the development of Tabang/Pakar has driven a significant increase in production, while the company continues to expand its infrastructure to support production capacity of more than 60 million tons per year.
With this business model, Bayan combines several highly strategic advantages: large coal resources, competitive production costs, integrated logistics infrastructure and access to international export markets.
If a change in control of Bayan were ever to occur, the implications for Indonesia’s coal industry could therefore be substantial.
What If Jhonlin and Bayan Were to Combine?
This is where the reported speculation becomes particularly interesting, If, hypothetically, Jhonlin Group were to acquire a controlling stake in Bayan, the combination could create a coal business with an exceptionally large production scale.
One industry analysis estimates Jhonlin’s coal production at approximately 24 million tons in 2025, while Bayan produced around 68 million tons during the same year. Theoretically, a combination of the two could therefore result in annual production of more than 90 million tons, although this is not an official company projection and would depend heavily on production quotas and actual output from both groups.
Such a scale would place the combined group in an extremely strong position within Indonesia’s coal industry., But production volume is not the only factor that matters. Jhonlin has developed strengths in logistics, mining contracting and supporting businesses, while Bayan possesses large-scale coal assets and established infrastructure.
As a result, there could theoretically be significant vertical and horizontal synergies if the two groups were ever to come under common ownership.
Market Speculation That Moved the Stock
Interestingly, the reported acquisition speculation also had a noticeable impact on the stock market. On 18 August 2026, Bayan’s shares were reported to have surged by nearly 20% following the circulation of acquisition speculation. At the same time, several companies associated with Haji Isam also experienced significant gains.
However, following clarification from Bayan and Jhonlin Agro Raya, market movements changed sharply. The episode demonstrates how sensitive investors can be to potential changes in the ownership structure of major Indonesian mining companies.
For the industry, it also highlights one important development: Jhonlin Group has grown to a scale where even speculation about its expansion strategy can attract significant market attention.
Jhonlin Is Not Relying on Coal Alone, What makes the Jhonlin story even more interesting is the group’s increasingly diversified business strategy. The group has expanded beyond coal into areas including palm oil plantations, biodiesel, logistics and minerals.
Coal, therefore, can be viewed as one of the group’s core businesses providing the cash flow needed to support expansion into other sectors. This strategy distinguishes Jhonlin from mining companies that remain primarily focused on coal production, Jhonlin is gradually building an integrated business ecosystem, with coal remaining one of its major engines of growth.
From Batulicin to a National Mining Powerhouse
Jhonlin Group’s journey reflects a major transformation in the group’s business structure. Starting from mining and contracting activities in South Kalimantan, Jhonlin has evolved into a diversified business group with interests across multiple sectors.
Today, with its growing coal production scale and expansion into minerals and other industries, Jhonlin can no longer be viewed simply as a regional coal player, And if the reported Bayan speculation were ever to become a genuine transaction, Jhonlin’s position in Indonesia’s mining industry would undoubtedly enter a new chapter.
For now, however, Bayan remains Bayan and Jhonlin remains Jhonlin.There has been no confirmation of any acquisition of the reported 62.2% stake. What exists at this stage is market speculation, a reported transaction value of approximately US$5.5 billion, and clarifications from the parties involved, And that is precisely what makes the story so interesting.
Is the reported Jhonlin interest in Bayan merely market speculation, or could it signal that Haji Isam’s ambitions in Indonesia’s mining industry are becoming increasingly substantial?
For now, the market is still waiting for the answer.
One thing, however, is already clear: Jhonlin Group is emerging as an increasingly influential force in Indonesia’s coal industry.
For advertising and subscriptions, please contact us via WA Or Email
Need a research report? Please visit CDMI Consulting